How To Write An Effective Audit Planning Memo In CPA Canada Cases

If you have selected Assurance as an elective in your CPA Canada PEP, or it’s your role for the CFE, writing an effective audit planning memo will be the key to achieving multiple competent grades. Let’s walk through the 4 steps of writing an effecting audit planning memo: Risks, Approach, Materiality, Procedures (abbreviated as RAMP).

1. Identifying Overall Financial Statement Level (OFSL) Risk 

Your first step in writing an audit planning memo will be to assess the overall financial statement level risks (OFSL). OFSL represents the risk of an audit engagement and risk of material misstatements (RMM). This assessment will be the foundation of determining what approach should be used to gather the appropriate evidence, the level of materiality we should accept, and the procedures required to form an audit opinion. 

It’s important to analyze case facts for factors that either increase or decrease the level of risk. A well-rounded risk response will contribute some form of a balanced response between the two. As you read the case initially, mark factors you can refer back to for this assessment opportunity.

For example, in the case below, the second paragraph says: “We’re growing at an incredible pace and we can’t keep up.” This is a trigger that increases the audit risk.


When writing your response, using bullets is a great strategy to use time effectively. Each bullet should discuss what the risk is and why the impact increases or reduces overall risk. Students who don’t achieve “Competent” are often the result of not having a sufficient amount of risks, or lacking depth in the risk impact. Be sure to only discuss new risk factors for this year.

Some common risk factors include:

  • Bank will be relying on bank covenants imposed on Company ABC. This increases OFSL risk as there is a risk of management bias to ensure financials meet the covenant.
  • There are several F/S errors present. This increases OFSL risk that there are additional accounting errors that have yet to be identified.
  • We have audited Company ABC for several years. This decreases OFSL risk as we are familiar with the business and their processes.
  • Company ABC has implemented a new software this year. This increases OFSL risk as we are unfamiliar with the controls surrounding the new software and this could be resulting in errors in the financial statements.

Be sure to conclude if the OFSL is high, moderate or low, and why (i.e. high because factors increasing risk outweigh factors that decrease risk). The vast majority of the time you’ll conclude the OFSL risk as high due to the nature of CPA exams.

For example, here is an effective way to write the risks and conclude:


2. Identifying the Audit Approach

To determine the overall approach for gathering audit evidence, assess the control risk on an overall basis. If controls can be relied on, typically a combined approach will be used. If controls are determined to be weak, a substantive approach is concluded. To conclude on this, identify case facts related to the control environment, the nature of the business, and explain the impact of these items on the audit. 

Some common considerations include:

  • New systems and processes. Will increase control risk as these processes have not been relied on before and auditors are unfamiliar with them. 
  • Company ABC has multiple locations. This will make it difficult for auditors to visit and apply a substantive approach on all locations. 

For example, here’s how the approach was written for this mock exam case:
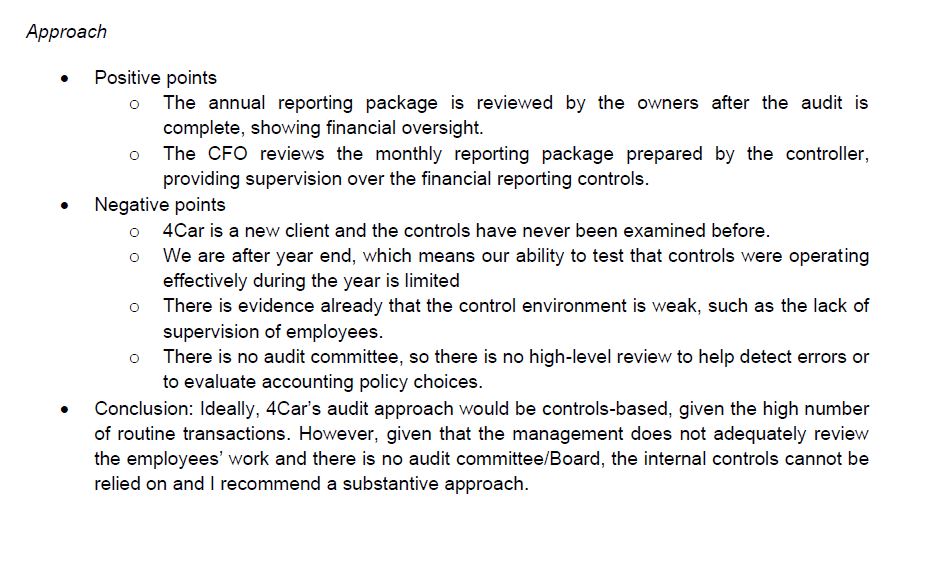
3. Determining Materiality

Materiality is a product of user needs, not audit risk. Therefore, you must identify the key users of the F/S and what their needs are. For example, potential investors may be concerned with overall profitability, but the Bank could be more interested in debt and equity based on covenants. Understanding these user needs will provide support for your chosen materiality base. Calculate materiality where possible on revised F/S (after corrections). 

Performance Materiality (PM) is based on the auditor’s professional judgment, and is associated with the risk of the engagement. This serves to mitigate errors that may not be detected during the testing phase. You should get in the habit of being able to include both overall and PM in your CPA case answers.

For example, here’s a complete materiality section:

4. Preparing Procedures

Procedures should be written for high risk transactions, accounts or assertions. When writing audit planning memo in CPA cases, it’s often written for all Financial Reporting (FR) issues. You should identify the specific risk, the related assertion and then the procedure. For this reason, procedures are often abbreviated to “RAP” (risk, assertion, procedure). Here’s an example of a risk: “Company ABC has pressure to meet a debt to equity covenant from the bank. There is a risk that due to management bias, the accounts payable account for what is owed is not complete”. Then write the assertion, which would be completeness.

Below are all the audit assertions:

Transactions/Events (Income statement): Completeness, Occurrence, Cut-off, Classification, Accuracy (“COCCA”)

Balances (Balance sheet): Completeness, Existence, Rights & Obligation, Valuation/Allocation (“CERV”)

Presentation and Disclosure: Occurrence, Rights/Obligations, Completeness, Classification/Understandability, Accuracy/Valuation

In CPA cases, we most often use the Income Statement and Balance Sheet assertions. You can remember them with the saying: IS COCCA CCERV’d in BoSton. There are more clever memory aids in my technical summary notes.

Assertions should have the GL accounts next to them. For example, Completeness (A/P) shows the assertion and account. This is not necessary when you write the RAP with FR issues though (see example below).  

Audit procedures should be specific and detailed by demonstrating a step-by-step process. To be specific, you can use case facts such as referencing specific documents, accounts or procedures outlined for this company. The procedure should address how the risk can be looked into and how evidence will be acquired. You should also make sure their procedures are practical and realistic and avoid general statements. It also helps to write the procedures below the FR issues, as opposed to combining them at the end, because they are closely related to FR issues and you can reference FR as you write.

For example, here’s an FR issues with the audit procedure below it:
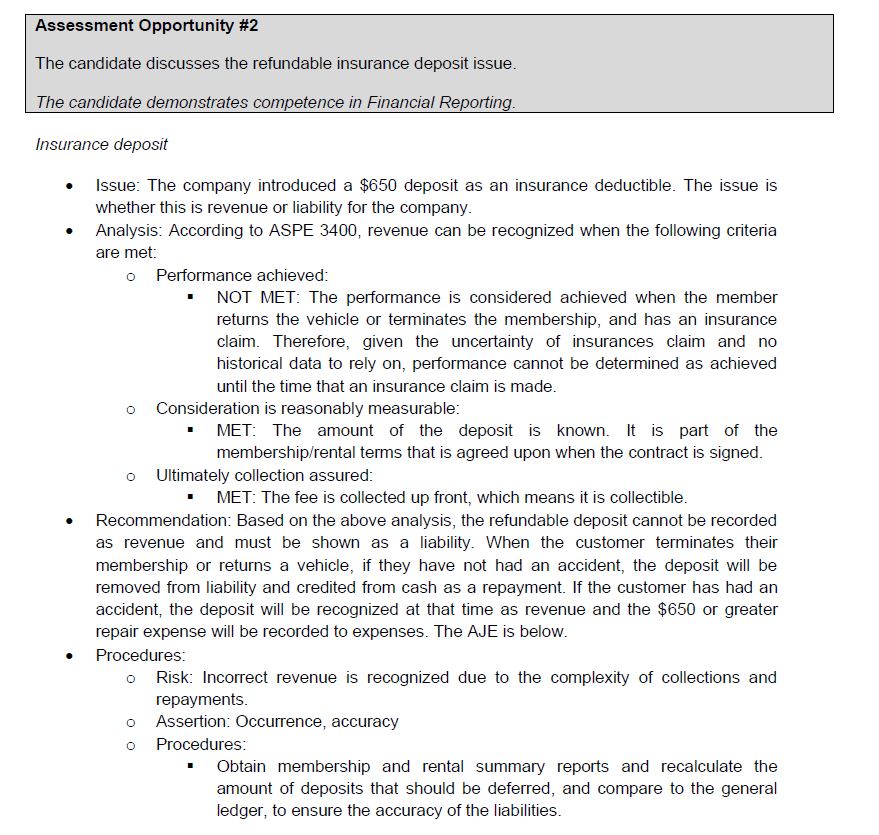
Some common procedures include:

  • Obtain copy of all materials related to R&D and review in accordance to above criteria to determine if costs should be capitalized
  • Obtain confirmation from management that ABC CO. plans to proceed with the R&D project to ensure the recognition criteria have been met
  • Discuss with management and corroborate their responses with the R&D team, as to whether the asset is likely to be fully developed and ready for market soon, and as to the progress made on the development.
  • Inquire and review if ABC Co. has complied with all terms of the agreement to determine if there are any additional unknown costs to include with the POC% calculation
  • Vouch a sample of the contract to the supporting contracts and any revisions made to these supporting contracts. Check for the date, contract amount, and any unusual terms.

Conclusion

Applying this structure for audit planning memo (APM) will ensure your assessment is complete and in-depth to achieve C (competent) grade. Practice the WHY and HOW of the impact for each step of the APM to make sure to hit depth.
Is a CPA Study Partner Right For You?

While many of us have studied independently throughout our education career, studying for CPA Canada PEP and CFE exams offers a unique opportunity to stay disciplined during the exam process. The following article provides several benefits to having a study buddy, while considering some limitations to overcome when selecting your study partner.

Benefits

  1. Holds you accountable: Since you will be creating a study schedule together, there is someone to hold you accountable to stay on track of timelines, case deadlines, case time constraints, etc. You’ll likely be meeting each other at set dates, so this forces you to finish your part before the meeting, thus helping you meet deadlines.
  2. Helps with your weaknesses: Your study partner could bring a unique CPA study skillset to the table to balance some of your weaknesses. This provides the opportunity to discuss complex topics and bounce ideas off of each other. This could also be helpful in learning from each other for creating a case plan and identifying case triggers.
  3. Supports with debriefs: Your study partner provides additional support for debriefing your CPA cases objectively. While CPA / facilitators will conduct marking still, it allows you to discuss competencies with someone, as opposed to only reading the feedback guide.
  4. Gives new insights: Reading and marking someone else’s cases gives you a unique insight into a new thought process and structure for cases that you may find helpful to adapt.
  5. Helps with learning: For technical review, there is the opportunity to split up difficult technical material between you two. You can each summarize the topics and teach them to each other. Explaining the information to someone else is a great way to test your understanding on the topic.
  6. Provides encouragement: Your study buddy offers you support and encouragement during the process. While you may have others in your life you can rely on, your study buddy is easily able to identify with your CPA journey.

Drawbacks and other considerations

  1. Different schedule: Your study partner may have a different working schedule, and studying alone would give you more flexibility. It would be beneficial to find a partner within your work or school to mitigate this. A virtual study partner could be just as effective as an in-person partner.
  2. Different expectations: Your study partner may not have the same expectations, work ethics, or skill set as you. This could hold you back from focusing on your main areas of concern. Finding a partner you know and trust as well as someone in the same CPA elective as you would be effective. A study partner who took a different elective can also help as they will have a better understanding of the competencies that you’re weak at.
  3. Time consuming process: Finding a study partner can often be a time consuming process. If you don’t know anyone in the program with you, there are several online resources to find a partner in your area. You can find a study partner at Gevorg CPA’s Facebook and WhatsApp groups here.

Overall, having a study buddy can be an asset but also an added variable to consider in your study plan. The shared motivation between study partners help foster a positive and confident study environment to ensure you both continue to push through the challenging times.

Find a CPA study partner

If you need helping finding a study partner, join my CPA PEP, CPA CFE Review and CPA PER Review courses where I will help you connect with like-minded students and ensure both of you succeed.

September 2021 CPA CFE Cases and Answers (Download)

Update: Please see these updated posts for May and September 2022 CFE exam cases download:

Similar to prior Common Final Exams (CFEs), the September 2021 CFE had Day 1, 2 and 3 cases. The following Day 1 cases were tested:

September 2021 CFE:

  • Waste Disposal Incorporated (WDI) v2 (download)
  • Distinct Hotels Corporation (DHC) v3 (download)

The following Day 2 and Day 3 cases were tested in September 2021 CFE:

  • Day 2 (download):
    • Farm Fresh to You Inc. (FFTY) (300 minutes)
  • Day 3 (download):
    • FenceCo (FenceCo) (90 minutes)
    • HSE Inc. (HSE) (80 minutes)
    • Amped Transit Ltd. (Amped) (70 minutes)

For the September 2022 CFE, the following Day 1 cases will be tested:

  • Waste Disposal Inc. case (WDI) v3
  • CanDo Fitness (CFL) v1

Where can I get these cases?

You can download by clicking on the hyperlinks above.  If you are registered for the Capstone 2 module for Summer 2022, you will receive these cases at the module. You can also simply download using the links above. If you are someone challenging the exam, such as an internationally trained accountant applying under MRA/MOU, also download using the links above.

Where can I get the solutions?

I have written my version of the solutions to September 2021 CFE cases, which you can get from here. The official solutions will be released in May, 2022, per CPA Canada’s announcement. 

How do I prepare for the CFE?

There are several prep methods for the CFE. You will need to focus on these three items:

  1. Technical knowledge
  2. Case writing skills
  3. Strategy

I speak a lot about these items on my YouTube channel and webinars. You can check out my latest webinar.

Technicals:

  • Know the key topics on each of the competencies
  • Distinguish depth from breadth
  • Debrief

Case writing skills:

  • It’s all about following the CPA Way
  • Know your case inside out
  • Integrate throughout the case

Strategy:

  • Prepare a study plan
  • Obtain study materials
  • Get support and resources

Pass the CPA Canada CFE Exam

I’m Gevorg. I’m an instructor and a CPA exam coach. If you want coaching with me, sign up for my CPA CFE Review Course, for a comprehensive prep package.

CFE Review by Gevorg CPA

4 Tips for Planning Your CPA Canada Goals for 2022

With the start of the new year, it’s the perfect time to make a clean slate and start thinking about what you want to accomplish in your CPA studies during 2022. Setting the standard as easily as possible will allow you to best use your time. This list will help you get started on how to set your new goals to ensure you reach your milestones, meet deadlines, and are kept accountable.

1. Evaluate yourself

To start planning for a goal, you should consider the things that you want to achieve. Categorizing what is important to you will allow you to create workable plans to get results. Be sure to write down these concepts. Individuals that write out objectives are more likely to accomplish them!

2. Define your goals

Once you have a high-level picture of your desires, you can get specific and define a course of action. Whether your goal is to complete all your PEP courses, pass the CFE, or achieve level 2 in PERT, ensure your goals are distinct and attainable. These goals should be separated into long and short term actions based on your priorities and your position.

The most effective way to set goals is by using the SMART method:

  • Specific – Being specific makes it easier to focus on a course of action. For example, instead of having the goal to study more, try being specific about the time you plan to study at, for example, 6pm to 8pm everyday.
  • Measurable – Be sure you can evaluate whether the goal was met. For example, aiming to achieve C in most AOs by the end of a module.
  • Achievable – Be realistic in what you can attain for the given year. Keep in mind CPA timelines of exams, work commitments, etc. to determine what is accurate for you to invest your time in given the resources available to you.
  • Relevant – Be sure to ask yourself if the goal is realistic and relevant to achieving your goal. For example, if your goal is to pass the CPA Tax exam, your goals should be focused on the Tax module, tax studying, etc.
  • Time-specific – Make sure your goals are consistent with your academics, work schedule and other responsibilities. Try to establish deadlines for each step of the process.

3. Execute your goals

As you execute and be consistent with your goals, priorities and circumstances may change. Your goals may evolve over time. It is important to recognize what is working and what is not, and revisit your goals frequently. For example, you may become unexpectedly busy at work, and using your lunch break to study may no longer be realistic. While it can be challenging to accept, it is important to recognize how a new or modified goal is a better course of action.

4. Overcoming Challenges

As you face certain challenges, you can set a goal on that particular issue. In some cases, overcoming a challenge might mean enlisting help. For example, if you are struggling with the CPA Core 2 module, it may help to find an appropriate tutor or study group.

There is no better time to start thinking ahead for what you want out of the upcoming year. It is not enough to have intentions, but the right framework to accomplish an idea. Setting goals will provide you with a greater sense of motivation and confidence. Be sure to reward yourself for your accomplishments!

Get effective CPA exam coaching

If you need helping passing your exams and completing PERT at Level 2, check out CPA PEP, CPA CFE Review and CPA PER Review courses for a comprehensive prep package and coaching.

Solving ASPE Loyalty Program AOs in CPA Canada PEP and CFE Cases

One of the key skills to assessing a financial reporting AO within a CPA Canada exam is understanding the differences between financial frameworks. We dove into depth of applying IFRS 15 to Loyalty Programs in a recent post. Where IFRS 15 provides specific guidance in the application of the standard, ASPE 3400 is judgement-based for recognizing and measuring revenue.

Example of ASPE 3400 Loyalty Program AO

Using the same example, consider the loyalty program of Entity A that sells shoes. For every $1 worth of shoe purchases, a customer receives 1 loyalty point. These points can be spent on purchases from Entity A and each point equals $0.10 worth of purchases. Based on historical trends, Entity A expects 5% of points to expire being unredeemed. That’s to say, it’s expected that 95% of loyalty points will be redeemed. So far, Entity A has sold $1,000 of shoes during the period. Assume no liability has been recorded in Entity A’s financial statements.

Analysis

The amount of revenue to be recorded needs to be assessed for Entity A. Under ASPE, this is based on a risks and rewards model, as opposed to IFRS 15 where control is the primary indicator. In this case, Entity A has an obligation to provide rewards to the customers that have earned them and collected loyalty points. This will trigger a need to assess whether a liability exists and should in fact be recorded.

To assess a liability under ASPE, the following factors should each be discussed using case facts:

  • Obligations arising from past transactions or events
  • Settlement may result in transfer or use of assets
  • Provision of services or other yielding of future economic benefits

Measurement

Since the customers earn 1 loyalty point for each dollar spent, you must estimate the amount of points that are outstanding at the end of the period. Given that $1,000 sales have occurred, approximately 1,000 points are outstanding. To determine the amount of liability that should be accrued, the points need to be valued. Since 1 loyalty point is redeemable for $0.10 worth of purchases, it could be estimated that $0.10 x 1,000 points = $100 as the cost to Entity A (or $0.10 value per point). Factoring in the likelihood of points to be redeemed, a more accurate estimate would be $100 x 95% = $95 for the liability.

Therefore, Entity A will need to accrue $95 liability at the end of the period. Entity A may be able to accrue a lesser amount if the percentage of points outstanding not redeemed changes.

Conclusion

As the points are redeemed, the liability will be reduced and revenue is generated. The liability will also be reduced when the option for these points expire.

The guidance for ASPE liabilities and revenue are presented in ASPE Sections 1000, 3290 and 3400.

Get effective CPA exam coaching

If you need helping passing your exams, check out CPA PEP and CPA CFE Review courses for a comprehensive prep package and coaching.

Solving IFRS 15 Loyalty Program AOs in CPA Canada PEP and CFE Cases

The core concept of IFRS 15 is the timing of revenue recognition, which is dependent on the timing of promises to be fulfilled by the entity. IFRS 15 provides significant guidance that can be applied to various situations retailers face, such as the treatment of customer loyalty points. Understanding loyalty programs is critical to foreseeing the liability a company owes and is a great topic for CPA Canada to test your IFRS 15 knowledge.

Example of IFRS 15 Loyalty Program AO

For example, consider the loyalty program of Entity A that sells shoes. For every $1 worth of shoe purchases, a customer receives 1 loyalty point. These points can be spent on purchases from Entity A and each point equals $0.10 worth of purchases. Based on historical trends, Entity A expects 5% of points to expire being unredeemed. That is to say, it is expected that 95% of loyalty points will be redeemed. So far, Entity A has sold $1,000 of shoes during the period.

Analysis

In this case, this option provides a material right to the customer that it would not receive without entering this contract (the purchase of shoes). It also gives the customer the option to acquire additional shoes at a price lower than the stand-alone selling price of the shoes in the future. This transaction involves committing to two performance obligations:

  • Goods purchased
  • Rights related to the loyalty points.

Because of this, it is necessary to estimate the stand-alone selling price of the option to allocate based on the separate performance obligations. For case writing, these criteria should be discussed with application to specific case facts. Write using the IFRS 15 5-step model and analyze the two performance obligations.

This estimate should account for the following factors:

  • Discount the option gives
  • Discount the customer could receive without the option
  • Likelihood the option will be exercised

Measurement

First, you must calculate the stand-alone price of the option. This is equal to the amount sold, factoring in the value of the points and point redemption rate ($1,000 x $0.10 x 95% = $95). The total transaction value is equal to the initial purchase value plus the value of the option ($1,000 + $95 = $1,095).

The amount sold ($1,000) should then be proportionally allocated to the loyalty program as a credit to accounts payable, and allocated to the product sales as a credit to revenue upon the initial sale of shoes:

  • Allocated to the loyalty program = $1,000 x ($95 / $1,095) = $87
  • Allocated to the sale of shoes = $1,000 x ($1,000 / $1,095) = $913
    (Note: As a check the total should equal the amount the customers have paid for (i.e. $1,000)).

Conclusion

If the likelihood of redemption cannot be determined, management may choose to assume 100% redemption or recognize revenue to the points on redemption. Revenue will also be recognized when the options for these points expire.

For some additional guidance on IFRS Loyalty Programs, check out paragraphs 26, B39-B43.

Get effective CPA exam coaching

If you need helping passing your exams, check out CPA PEP and CPA CFE Review courses for a comprehensive prep package and coaching.

How to Debrief a CPA Canada Case

As you continue on your journey towards your CPA designation, being able to debrief and achieve competency efficiency becomes increasingly important. In fact, debriefing will likely become your main study method.

1. Know when to debrief

The most effective way to debrief is not too long after writing the case. This way, the case facts are fresh in your mind and time can be saved from avoiding having to read the case again. Debriefing the case the following day will be more realistic and effective in managing a work-study balance.

2. Understand the marking competencies and how it relates to you

CD – Know what you completed very well, but not always the optimal rank.
C – Know what you you completed correctly
RC / NC – Know what you were on the right track on, but needed to include more
NA – Know what assessment opportunities you missed

The objective is to achieve a C, noting that achieving a CD might mean you spent too much time on one assessment and could have used that time elsewhere. The goal is to do enough required for each assessment. Focus your attention on the assessments that are not at a level C.

3. Review the sample responses

A sample response will show the level of depth/breadth expected of a candidate writing under the time constraints. Review how you could have approached a quantitative and qualitative analysis more efficiently, what case facts might have been missed, etc. Think “What more did I need to include in my response?”.

4. Review the solution

The solution demonstrates a “best” response, meaning, under no time constraints. It should be noted that candidates are not expected to strive for perfection. However, the solution provides a resource to ensure that your notes are complete.

5. Create and organize your notes

Organize your notes by topic (i.e. Financial Reporting, Tax, etc.) and continue to add to them each debriefing session. Watch as your knowledge on the topics expand over time.

6. Give enough time to the debrief process

Do not rush the process of debriefing and making notes. Typically debriefing a case should take as long as it took you to write the case (i.e. debrief 2 hours for a 2 hour case).

While debriefing can be an intimidating process, it is a necessary process to ensure you are making the steps to improving with each and every case. Building this habit will make the CPA journey much more manageable.

Get effective CPA exam coaching

I’m Gevorg, I’m an instructor and a CPA exam coach. If you need helping passing your exams, sign up for my CPA PEP and CPA CFE Review Course for a comprehensive prep package.

How to Account for Future Income Tax (DTA/DTL) IAS 12 in CPA Canada PEP and CFE

CPA Canada Knotia eBook explains income tax accounting in Chapter 23. However, student struggle understanding the steps in calculating and journalizing the deferred tax asset (DTA) and deferred tax liability (DTL) in cases. Here is a quick summary.

Explanation of future income taxes (FIT)

The idea behind future income taxes (FIT) is to book a liability for future payment of taxes (due to differences in accounting vs tax income). We have to do this because this is money we owe in the future to CRA, like accounts payable we owe to vendors, and GAAP says all obligations must be shown on F/S.

We have these differences for many reasons. A common one is the depreciation rate. We record depreciation at one rate while CCA is at another rate. There is a difference that is owed and we record this difference to FIT liab and FIT expenses.

Part A: Example

Step 1a: Calculate temporary differences 

To determine the temporary differences, deduct tax base from accounting base.

[Temporary difference = Accounting base – tax base]

Note: Both the Accounting base and Tax base are usually given in the case.

Step 1b: Determine if taxable or recoverable temp difference

Using the results from Step 1a:

  • If the total temp diff is negative => Deductible => DTA
  • If the total temp diff is positive => Taxable => DTL

Step 2: Calculate DTA/DTL

To calculate DTA/DTL, multiply the tax rate by the total temp differences from Step 1a.

[DTA/DTL = Tax rate % x total temp diff (from Step 1a)]

Step 3: Adjust DTA/DTL to actual

  • step i) Look at the balance of DTL/DTA from prior year in B/S (this should be given in the case)
  • step ii) Look at the balance for current year (calculated in Step 2)
  • step iii) post an AJE to adjust the balance from prior to current.

Example from the eBook

The following is the breakdown of the example seen in the CPA Canada eBook Chapter 23:

  • Step 1a: We found it’s -$10,000 (the eBook doesn’t show negative, but it is negative since accounting base is smaller than tax base)
  • Step 1b: It’s negative, so DTA.
  • Step 2: DTA: $10,000 × 45% = $4,500
  • Step 3: AJE
    Prior = $10,400 DTL
    Current = $4,500 DTA
    AJE:
    Dr DTL $10,400 (to remove prior from B/S)
    Dr DRA $4,500 (to add current to B/S)
    Cr Deferred tax recover $14,900 (plug to balance the entry)

Part B: Memo

IAS 12 Income Taxes

Calculations/quants are half of the marks. You won’t get C by simply following the above steps. It’s important to quote the technical from CPA Canada Handbook correctly. This is illustrated below.

Issue:

ZZZ Co. has provided information regarding the income taxes. The issue is what the deferred tax provision calculation for 20XX should be.

Analysis:

  • According to IAS 12, para 5, temporary differences are differences between the carrying amount of an asset/liability in the statement of financial position and its tax base.
    • As seen in App X, there is a total deductible temporary difference of $XXK (NOTE: calculate per above steps 1a, 1b, and 2)
  • Furthermore, according to IAS 12, para 5:
    • DTA are the amounts of income taxes recoverable in future periods in respect of deductible temporary differences, the carryforward of unused tax losses, and the carryforward of unused tax credits.
    • DTL are the amounts of income taxes payable in future periods in respect of taxable temporary differences
      • This means DTL rise from taxable temporary differences, while deferred tax assets (DTA) rise from deductible temporary differences. Given that the total $XXK is a deductible temporary difference, this amount is a DTA.
  • Furthermore, according to IAS 12, para 24, DTA shall be recognized for all deductible temporary differences to the extent that it is probable that taxable profit will be available against which the deductible temporary difference can be utilized
    • MET: ZZZ Co. is growing rapidly with positive financial results. There are no indications that a taxable profit is not probable in the near future.

Recommendation:

Based on the above analysis, I recommend recognizing DTA of $XXK and Deferred tax recovery of $XX, per AJEs in App X. (NOTE: calculate per above Step 3 )

Got questions about the CPA program? Contact me for advice: http://gevorgcpa.com/contact

Your Support Options with CPA Canada PEP and CFE

CPA Canada exams are grueling and require hours of dedicated study and practice. At some point, you may feel that you need supplemental support. Here are your options.

Option #1: One-on-one CPA tutor

You can hire a CPA tutor to sit down with you, act as your coach and provide one-on-one help. Tutors usually don’t have supplemental cases, they use CPA Canada’s cases and answer your questions. You pay per hour and the usual fees are $60-$100/hr (depending on experience).

Option #2: Case marking

You can hire someone mark your cases and pinpoint the areas to work on. The difference with this option is that you don’t have live sessions with someone, the feedback is done on paper, similar to CPA facilitators. You pay per marked case and the fee is usually $40-$100 (depending on case length).

Option #3: Supplemental cases, practice drills

You can get supplementary materials such as extra cases, drills, study notes. With this option, you would study independently using the materials. The prices vary greatly depending on the type of material you purchase.

Option #4: Coaching program

You can sign up for a coaching program. The great thing about a CPA coaching program is that it’s an amalgamation of above support sources: You receive the live coaching, supplementary materials, and case marking.

Which one is best for you? It depends on your circumstances and your budget. If you failed your exam twice, I highly recommend hiring a one-on-one tutor or signing up for a coaching program. These resources will help you find where you’re going wrong and help you correct and improve it.  If you are taking your module for the first time, you may want to purchase supplemental materials and study independently. After a few weeks, if you feel that you’re struggling, consider upgrading to the other options.

Got questions about the CPA program? Contact me for advice: http://gevorgcpa.com/contact