Should You Explain the CFE Day 1 Situational Analysis Framework?

CPA Canada’s Day 1 CFE requires a very different approach than the remaining two CFE days. The layout of the case is based on your Capstone 1 case, with little technical criteria application. Before even starting to assess the strategic issues, you’ll be required to complete a Situational Analysis Framework. Most candidates find difficulty in understanding the detail requirements to completing the situational analysis. Below is a guide to clarify the depth needed when starting your CFE Day 1 response.

Day 1 Situational Analysis

A major component to being successful on Day 1 is to have a strong situational analysis in your answer. You should follow the below format:

  • Identify the mission, vision, values of the company and if / how each has changed from Capstone 1.
  • Identify any key success factors (KSFs) of the company (typically 4 to 5 is a good rule of thumb).
  • Outline any goals and objectives of the company or key stakeholders.
  • Identify any constraints (i.e. financial or other) and covenants the company has to comply with.
  • Complete an updated external / internal analysis in the form of SWOT analysis (making sure analysis is well-rounded).
  • Perform a financial assessment, including a ratio analysis, call out of key financial items and/or YoY financial (i.e. profitability) changes.

You don’t need to memorize the entire Capstone 1 case, but the above key areas need to be studied well because you’ll use them in your CFE Day 1 answer.

Details of Situational Analysis 

The situational analysis itself should not take more than 20 minutes, but you do want to complete it fully, because you’ll be linking each of your issues back to the points from it throughout the remainder of the exam.

Most components of the situational analysis can be written in point form. For example, listing the KSF as they appear in the case with no additional explanation is fine. You will notice in the below example of KSF, the points are not explained further with implications, but just written in point form.

As you link back (“integrate”) to some of these points in your strategic issues, they would then be elaborated further with implications.

What about SWOT?

I don’t recommend to explain SWOT. You should write short point form case facts, such as the example below.


Conclusion

Situational analysis is required to successfully pass Day 1 of the CFE, however you don’t need to explain it. 

Summary:

Day 1 SA section How to format
Mission, vision, values Point form, don’t explain
KSFs Point form, don’t explain
Goals/objectives Point form, don’t explain
Constraints Point form, don’t explain
SWOT Point form, don’t explain
Financial assessment Explain briefly

Extra Resources

Day 1 pass rates have been falling in the recent CFEs. To help students succeed, I provide templates, extra practice cases, exercises, and live classes to master and pass CFE Day 1. Extra resources are available at the CFE Review.


Why You Should Take PM Elective After Core 2

After you’ve passed both Core 1 and Core 2, you’ll be at the point in your CPA Canada PEP journey where you have to choose your first elective. There is no right or wrong on which elective to take, but depending on your strengths, weaknesses, desired CFE role and career goals, you may choose one elective over the other.

While there are several pros and cons to each elective, having just finished Core 2, there are several advantages to taking Performance Management (PM) as your next elective. Here’s why.

PM has similar quants (calculations)

Both Core 2 and PM blueprints focus on Management Accounting (MA), Strategy and Finance competencies. You can smoothly transition your knowledge and studying techniques from Core 2 to PM because most of PM’s technicals are like Core 2 and still fresh in your mind. 

For example, here’s the exam blueprint for Core 2:

And here’s the exam blueprint for PM:

You can see that MA, Strategy and Finance are the key competencies in both.  (Note: You’ll notice above that Finance is not tested in PM’s objective-format portion (MCQs). This is misleading because MCQs are a small part of the PM exam while Finance plays a big role of the case portion. Ensure you study Finance well for the PM exam.)

Some common calculations (quants) that show up both in Core 2 and PM include:

  • CVP (break-even, contribution margin analysis)
  • Product mix
  • Variance analysis (price, usage/quantity)
  • Sensitivity analysis
  • Sourcing (inhouse, outsource)
  • Constraints (scarce resources)
  • Relevant costing
  • Activity-based costing (ABC)
  • Transfer pricing (TP)
  • NPV and IRR
  • Ratio analysis (profitability, liquidity, efficiency)
  • Valuations
  • Payback period

The biggest challenge with quants for candidates is being able to identify the most appropriate analysis (“quants tool”) to choose when answering an AO. This is a skill you would have developed and strengthened during Core 2 that will help contribute to success in PM with a similar calculation structure. The MA Templates toolkit will help you refine and master these calculations.

PM has similar qual

PM and Core 2 have qualitative components on similar subject matters. While studying for Core 2, you would not have studied much Financial Reporting (FR), Assurance, or Tax criteria. Because of this, taking a different elective would require you to shift focus and start reviewing these topics again from scratch. For example, if you take PM and Assurance as your electives, and you take Assurance right after Core 2, it will require you to re-learn Assurance and FR concepts you’ve already forgotten from Core 1.

Additionally, Strategy & Governance takes up about 50% of the PM exam. Using the approach of being concise and specific with explanations, as well as integrating case facts, is critical for getting C in PM qual. This is a skill you would be familiar with from Core 2. You would also be in the habit of being “big-picture” focused, in aligning the company’s values or user objectives to the overall strategy. This is again prevalent in PM.

Managing your time effectively while balancing various quant and qual analyses was critical during your Core 2 studying. This time management skill is equally important during the PM exam and will make transitioning your study techniques efficient and give you an advantage when prepping as well.

Some common qualitative assessments (qual) between Core 2 and PM include:

  • Integrating mission, vision and values (M/V/V)
  • Addressing strategic decision making (use of SWOT, Porter’s 5 Forces, PESTEL)
  • Responsibility centers (evaluating performance)
  • Decision pros vs cons (outsourcing, capital investment, acquisition)
  • Pricing strategies (demand-based, cost-based, bundling)
  • Risk management (using RIM format)
  • Governance structure (i.e. evaluating current board of director’s structure and provide recommendations using WIR format)
  • Balanced Scorecards (BSC)
  • KPIs
  • Financing Sources

The Core 2 and PM supplemental practice cases and MCQs provide good practice on above concepts.

Extra resources

Because much of what you have learned and successfully demonstrated in Core 2 is necessary for being successful in PM, I suggest to take PM directly after Core 2 for a seamless study transition. From both qualitative and quantitative perspective, there are several overlaps in subject material that you will already have an understanding on that could be tested again in PM. This will also advance your knowledge in key concepts that will be tested during Capstone 1 and Day 1 of the CFE. Extra study resources can be found in the Core 2 and PM Review courses.


How to Solve DAIS in CPA Canada PEP and CFE Exams

With increased focus on big data and emerging technologies in our day-to-day lives and professional careers, CPA Canada has placed more focus on Information Technology (IT) and Data Analytics and Information Systems (DAIS) in the competency map. Despite previous inclusion on the CPA Competency Map, many resources like the E-Book, weekly practice cases (PCs) and integrated problems (IPs) have not explained DAIS sufficiently. This article will help you prepare for DAIS issues in the CPA Canada PEP and CFE exams.

Data Analytics and Information Systems (DAIS) topics

Though DAIS affects all competencies, Management Accounting (MA) is the most commonly tested area. The following sections have been added to the MA competency regarding information and decision making:

  • Data visualization of financial and nonfinancial data
  • Dashboards, graphs, tables report design
  • Communication of information for quality decision making
  • Framing information recognizing uncertainty
  • What is the value of information in the decision-making process?
  • Transformation of data to decision relevant information
  • Creation of intellectual property and knowledge development
  • Ethical use of information
  • Dimensions of information quality – relevance, ease of use, integrity, timeliness
  • Types of data and their attributes (nature, sources, format, timing, extent and level of aggregation)
  • Professional skepticism regarding data
  • Information quality and the impact of processing models
  • Data cleansing
  • Data structure and standards
  • Data extraction and import
  • Data life cycle

I don’t suggest spending the time to study above concepts. They may come as MCQs in PEP exams, but you’ll be able to find the right answer through logical thinking. Instead, study data visualization, because this is the most commonly tested DAIS topic on the cases and CFE.

Data visualization (charts)

Using the CFE September 2021 Day 2 FFTY case and solution, let’s walk through an example of how data visualization (charts) DAIS can be tested on a case. I will walk through the first three charts. (Note: If you don’t know how to approach CFE level cases, follow the steps below as I break down the case and the solution).

Step 1: Required

On page 15 of the case, under the Excerpts from the management committee meeting appendix, it’s indicated that they would like you to analyze the data (charts and graphs) provided in Appendix VI and provide any recommendations for improving operating profits.

In the background information (page 3 and 9), we are told that FFTY is a grocery store chain specializing in locally-produced, farm fresh foods. FFTY produced three types of products:

  • 1) Freshly prepared hot and cold food
  • 2) Non-perishables (eg. canned and dry goods)
  • 3) Perishables (eg. fruit, vegetables, dairy and meat)

Step 2: Analysis

We see the charts in Appendix VI (page 18) and our task is to analyze the charts and provide a recommendation.

First set of charts are seasonal trends. We see that the perishable “Cost of goods sold” line is higher than the revenue line for the months of December to February. We also see that the COGS are not a straight-line.

To analyze the chart, we’ll follow the steps below:

  • (1) We write what’s the issue that the chart reveals (ie, perishable items are being sold at a loss during winter)
  • (2) We explain the results (ie, we assess why this may be occurring. For example, it may be harder to get organic perishable items during the winter months due to lack of access. We also state the impact. We discuss what the results mean for the company. For example, because the revenue is not enough to cover the costs, perishable items are generating a loss for FFTY during these months. It’s important to integrate case facts to achieve depth. On page 9 on the case, it says that “FFTY tries to keep prices for most items stable throughout the year”. This is contributing to the losses as the price remains constant during the periods when costs are higher.
  • (3) We provide a recommendation (the case says that “customers are willing to pay a premium for locally produced, whole foods” (Page 9), so customers are less price sensitive. We can suggest FFTY to increase the pricing of perishable items during the winter months.)

In summary, we’ll write in our analysis that perishable items are being sold at a loss, since COGS during winter months is higher than the revenue. This could be due to lack of access to organic perishable items and selling prices not being adjusted to cover the cost increase.

For non-perishables, we see that there’s decrease in non-perishable revenue during the summer months (July to September). Comparing with the earlier chart, we see increase in perishable revenue during the same time period.

We’ll write that there’s a decrease in non-perishable revenue during July to September months. This could be due to customers substituting non-perishable items with perishable ones during the summer.

The next seasonal trend is for freshly prepared hot and cold foods. We see that freshly prepared foods revenue is lower in the summer months.

We’ll write that freshly prepared foods revenue is lower in the summer months. This could be due to customers being away or having more time to cook their own food than purchase prepared food during those months. FFTY does not currently have seating areas for people to eat prepared foods, which could explain why the revenues are down.

Step 3: Assumptions

In addition to analyzing the charts, we’re also required to discuss data limitation and reliability of the charts. This is needed for C.

Always consider that you may not have access to the entire data set and must acknowledge that there can be gaps or unreliable information provided. To assess this, you will want to consider and discuss the following items:

  • When (i.e. year) the data was provided: Have there been significant changes since? In the case of FFTY, the data is from 2019 but the company saw growth and franchise expansion in 2020.
  • The source of the data: Who is providing the information? Do they have a bias? What systems is the data coming from?

Template for DAIS

Format your answer with IER + WIR.

  • IER means: Issue, Explanation (interpretation + implication + impact), Recommendation.
  • WIR means: Weakness, Implication, Recommendation.

You must write both (IER and WIR) to get a C.

In IER, we analyze the chart. We write what’s the issue based on the chart, explain (interpretation, implication, impact and relevance to the company), and give recommendation (specific, clear recommendation on what action to take).

In WIR, we discusses reliability of the charts. We discuss the weakness, implication, and recommendation.

Sample answer

Here’s a sample answer to the first three charts in this case:

Chart #1: Perishables:

  • Issue: Throughout the year, perishable are providing a reasonable gross margin. During the winter months (December to February), perishable items are being sold at a loss, since COGS during those months is higher than revenue.
  • Explanation: This could be due to lack of access to organic perishable items and selling prices not being adjusted to cover the cost increase.
  • Recommendation: Given that FFTY’s customers are willing to pay premium for locally sourced foods (ie, less price sensitive), FFTY should increase the pricing of perishable items during the winter months to cover the increase in costs.

Chart #2: Non-perishables:

  • Issue: There’s increase in perishable revenue during the summer months (July to September) and decrease in non-perishable revenue during the same period.
  • Explanation: FFTY tries to keep prices stable, the increase in perishable revenue is likely due to increased volume of sales. Given that customers are likely substituting non-perishable items with perishable ones during the summer, this appears reasonable.
  • Recommendation: FFTY could attempt to keep non-perishable revenue high during the summer months by offering a small discount on non-perishable items that pair well with perishable items.

Chart #3: Freshly prepared hot and cold foods

  • Issue: Freshly prepared foods revenue is lower in the summer months.
  • Explanation: This could be due to customers being away or having more time to cook their own food than purchase prepared food during those months. FFTY does not currently have seating areas for people to eat prepared foods, which could explain why the revenues are down.
  • Recommendation: Add seating areas which may help increase revenue during the summer months since there may be a group of customers who will purchase freshly prepared food to eat at FFTY.

Assumptions:

Below, I’ll discuss reliability and gaps in the information provided.

  • Weakness: Jim has used financial data only from 20X0, not 20X1.
  • Implication: There are some changes in 20X1, such as company growth and new franchisees, that could cause 20X0 not to be representative of 20X1 or of future years.
  • Recommendation: Use more recent data to get better analysis. 
  • Weakness: Jim used only two sources of data: the accounting system and the spoilage spreadsheet.
  • Implication: Data could be incomplete and not include all relevant information (eg popularity of certain brands or whether discounts are being used). This could result in poor decisions or inappropriate recommendations.
  • Recommendation: Seek additional sources of information (eg information in POS system should have useful data, such as which products are more popular and when products are being purchased). This would provide useful information for FFTY’s operational plans.
  • Weakness: Jim has used internal sources of information only.
  • Implication: Data could be incomplete, as external sources (eg industry statistics) are valuable in helping to interpret results.
  • Recommendation: Use industry statistics. They can be used to understand if FFTY is making good decisions (eg is FFTY’s strategy of keeping prices stable throughout the year different/same as its competitors).

(Note: For this AO, 3 IER and 3 WIR items were enough to get C. To be able to answer this AO, you needed to know the rest of the case and key case facts. Notice that I’m keeping the “issue” and “weakness” lines short; most of the marks are in the “explanation” and “recommendation”, you should focus on these. Though I wrote in bullet form, using two tables is better.)

Extra resources

CPA Canada will continue to test more DAIS in PEP and CFE exams, as the importance of analyzing data and innovating processes continues to emerge. To get extra resources on DAIS, check out my PEP and CFE courses.
 

FR Competencies for CPA Canada’s Core 1

Core 1 covers Financial Reporting (FR), Assurance, Tax and Finance competency areas. I’ve written about Assurance, Tax and Finance common topics in other posts, I’ll cover the FR topics here.

Common FR topics to know for Core 1

Here are some of the common FR topics you should know for Core 1:

  • Revenue recognition
  • Lease accounting
  • Inventories
  • Property, plant and equipment (PPE)
  • Intangible assets
  • Tangible asset Impairment
  • Provisions, contingent liabilities
  • Non-monetary transactions (NMT)
  • Related party transactions
  • Government assistance
  • Subsequent events
  • Financial instruments (FI)
  • Decommissioning provision
  • Non-current assets held for sale
  • Accounting for income taxes
  • Business combinations
  • Investment in Associates
  • Foreign currency

All FR topics that can be tested

The above is a condensed list of frequently tested topics. The full list of FR topics that you can be tested on are listed in the CPA Canada Competency Map.


Get Help with Passing Core 1

Sign up for the Core 1 Review program to get extra practice cases, study plan, engaging video lessons and personalized coaching with me.


Assurance Competencies for CPA Canada’s Core 1

Before starting Core 1, it’s useful to review topics that are going to be taught and tested in this CPA module.

Core 1 covers Financial Reporting (FR), Assurance, Tax and Finance competency areas. I’ve written about FR, Tax and Finance topics in other posts, I’ll cover the Assurance topics here.

Common Assurance topics to know for Core 1

Here are some of the common Assurance topics you should know for Core 1:

  • Audit planning memo (Risk, Approach, Materiality, Procedures)
  • Assertions
  • Audit evidence
  • Analytical procedures
  • Special engagements
  • Reviews
  • Compilations
  • Control deficiencies

All Assurance topics that can be tested

The above is a condensed list of frequently tested topics. The full list of Assurance topics that you can be tested on are listed in the CPA Canada Competency Map.


Get Help with Passing Core 1

Sign up for the Core 1 Review program to get extra practice cases, study plan, engaging video lessons and personalized coaching with me.


Failed CPA CFE 3 Times? You Still Have Options

CPA Canada allows candidates to attempt the CFE three times. At each unsuccessful attempt, candidates can appeal and ask for re-marking. After three unsuccessful attempts and remarkings, candidates will automatically be de-registered from the CPA PEP program. If you’re in this situation, here are some options to consider.

1. Request 4th Attempt at the CFE.

Officially, you have three attempts at the CFE. However, it’s possible to write it for the 4th time. Candidates can present a letter to CPA Canada asking for a 4th attempt.  To be successful in this request, you must have a situating that was extraordinary, outside of your control and well documented. 

I have consulted candidates and successfully got them the 4th attempt. 

Update 2025: Due to popular demand, I now offer a dedicated mini-course to help you prepare a strong 4th attempt case and PER extension requests. Click on the image below to learn more:

2. Wait until 2027

As you may know, PEP and CFE are being changed from 2027. The new CPA certification program will not have Core 1/2, electives, MCQs, nor CFE. It will not focus on technicals, but rather on case writing and decision making. At the time of writing this article, we don’t have official details on the new program structure, however you can choose to wait until 2027 and register into the new program.

3. Take the U.S. CPA.

To take the US CPA exams, you don’t have to be a US citizen or go to the US. You can apply online and study from Canada. US CPA costs less than the Canadian CPA and there are only MCQs and short-form answers in the exam. I wrote a detailed post comparing both designations here.

4. Get ACCA

Becoming ACCA is another good alternative. ACCA stands for Association of Chartered Certified Accountants, it’s a globally recognized designation with strong recognition in the UK, Asia, Europe, and it’s highly valued in Canada too. Canadians can enroll in the ACCA program without leaving Canada, study online, and write the exams in designated exam centers. 

5. Pursue the CFA designation.

CFA (Chartered Financial Analyst) is a good certification if you want to grow in Financial Planning and Analysis (FP&A) role. You can expect the same salary as a controller / director who’s a CPA. Read more about the CFA program here.

6. Pursue Masters in Accounting degree.

The Masters in Accounting (MAcc) program will teach you the same technical competencies as PEP and give you post-grad certification. Some employers consider MAcc to be equivalent to CPA. You can read more about MAcc program here. 

8. Become a Registered Professional Accountant (RPA)

Based in Ontario, the Registered Professional Accountant (RPA) designation lets members practice accounting services, including tax and compilations (CSRS 4200). 

9. Focus on your career.

I have worked with several managers in the finance/accounting departments who did not have CPA or other certifications. Instead, they had extensive work experience and great networking skills. Employers tend to look closer at what companies applicants worked for, not their education.

Conclusion

There are many viable alternatives to the CPA. Step back and assess your professional goals. If pursuing CPA was for growth and a high salary, consider other designations or careers. Don’t give up and stay motivated.

If you’re considering a 4th attempt or need help with next steps, enroll in my new 4th Attempt & CPA Extensions course to learn more.


What Can be Tested in CPA Canada CFE Day 2?

Day 2 of the CFE is considered by many to be the hardest of all CFE days. You have to ensure that you achieve depth (ie, score C/CD) in as many AOs as possible. This article will help you find the key areas to study and explain how Day 2 works.

Structure of Day 2

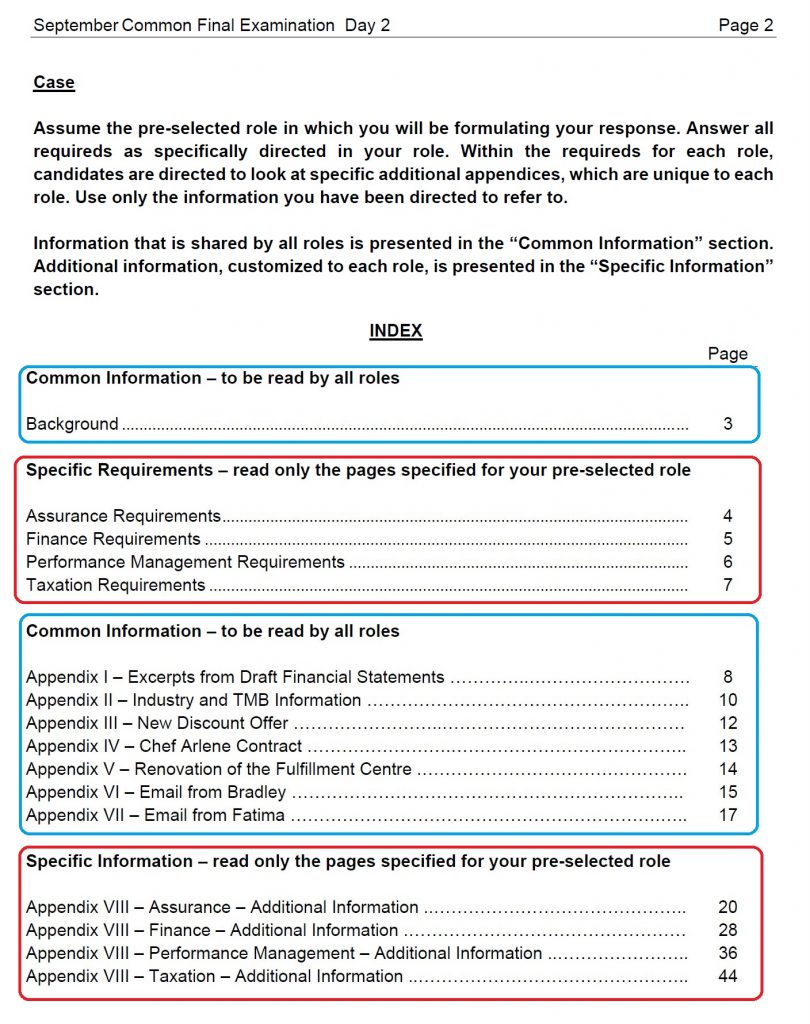
As I wrote in the Ultimate Guide to CFE blog post, Day 2 has one case that must be completed within 5 hours. It’s broken into two sections: Common AOs (blue below) and Role AOs (red below).

Common is the same for everyone writing the CFE. Role is based on the specific area that you choose and you have 4 options:

  • Assurance
  • Performance management (PM)
  • Tax
  • Finance

Common AOs

Common AOs test on FR and/or MA competencies only. The “and/or” here means you could get:

  • Only FR
  • Only MA
  • Mix of FR and MA

Based on recent CFEs, the common AOs contain a mix of the two (approx. 3 FR and 3 MA AOs). There are typically 6 AOs in the Common component. 

The complexity level of the common AOs is at the Core level (ie, same AOs as you’ve seen in Core 1 and Core 2). From my experience, the FR and MA AOs are more complex than in Core 1/2. For example, in recent Core 1 exams, basic revenue recognition AOs have been tested (ie, upfront non-refundable deposit, percentage of completion, right of return). While in recent CFEs, the revenue recognition AOs were lengthier and touched on non-routine, complex topics: royalties, multiple performance obligations, variable considerations, warranties, loyalty points, etc.

I recommend studying non-routine FR AOs as a strategy for Day 2 common component. Examples of non-routine FR AOs:

  • Revenue recognition
  • Financial instruments (FI)
  • Leases
  • Accounting for income taxes
  • Business combinations
  • Investment in associates
  • Earnings per share (EPS)
  • Foreign currency (FX)
  • Investment properties
  • Joint arrangements
  • Accounting policies, changes in estimates
  • Share based payment (SBC)
  • Employee benefits
  • Agriculture
  • Operating segment (IFRS only)
  • Interim financial reporting (IFRS only)
  • Borrowing cost (IFRS only)
  • FV measurement (IFRS only)

Having concise FR notes can help you quickly study the above topics.

For MA, the AOs are repetitive and touch on these topics:

  • Variance analysis
  • Break-even point (BEP)
  • Pricing
  • Data analytics and info services (DAIS)
  • Budget analysis

I recommend practicing different variations of above AOs to master them for CFE Day 2.

Role AOs

The role specific AOs are based on your selection from the four electives (roles) and any competency areas that fall within these categories (i.e. PM contains Strategy & Governance and MA, Assurance contains Assurance and FR). I recommend to choose your role based on your strengths and will likely be based on one of the electives you took during PEP. 

The level of depth is tested at the elective level (ie, same level as in electives). Typically, there are 7 AOs in your role, meaning you will spend more time on the exam discussing your role.

I recommend re-writing your role elective’s practice cases as a warm up during Capstone 1 to get ready for this component. For example, if you took PM as your elective, re-write all module PCs and any mock exam PCs you have for PM.

The recurring AOs tested in the CFE role components include:

Assurance:

  • Audit planning memo
  • Control deficiencies
  • Procedures
  • Special reports

PM:

  • Performance measures
  • Strategy (ie, mission, SWOT)
  • Decision analysis  – quant
  • Decision analysis – qual

Finance:

  • Valuation
  • Capital budgeting
  • Sources of financing
  • Ratio analysis
  • WACC

Tax:

  • Taxable income/payable – corp
  • Taxable income/payable – individual
  • Employee benefits

Strategy for Day 2

Your goal on Day 2 is to get as many “Competent” (C) grades as possible. It’s important that you achieve at least 2-3 Cs in FR or MA (one or the other). It’s also important you get at least 4-5 Cs in your role. This is needed to pass the Days 2/3 levels 2 and 3.

Conclusion

Day 2 will have no other competencies other than FR and/or MA, and your role. There are often surprises on the CFE, but the above listed topics are the most commonly tested. 

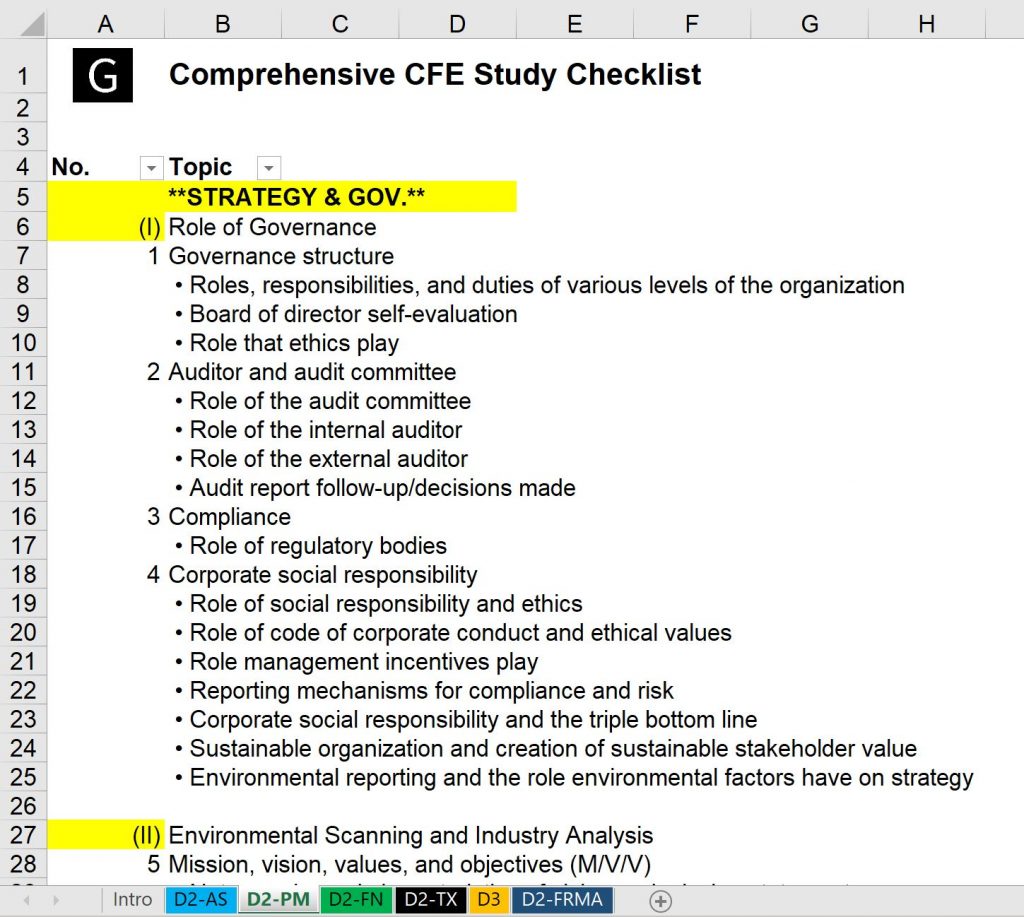
The popular CFE Review program contains all-inclusive list of all topics that can be tested on your CFE for each role, based on the Competency Map. You can preview the program here.


CPA Canada CFE Day 1 J.R. Pets (JRP) Mock Exam Case

The Capstone 1 J.R. Pets Inc. (JRP) case will be tested in September 2023 and September 2024 Common Final Exams (CFEs) on Day 1. The original Capstone 1 case will be made available to candidates enrolled in Capstone 1 and released publicly later by CPA Canada.

How do I prepare for JRP case for the CFE Day 1?

On CFE Day 1, you will be presented with the same JRP case and you will be required to analyze and answer new strategic and operational issues.

Follow these strategies:

  • Step 1: Study the Capstone 1 original case well: It’s important that you know the Capstone 1 case inside-out. You will encounter the same users and similar industry challenges. I suggest making notes of the following key situational analysis factors:
    • Users
    • Mission, vision and values
    • Key success factors (KSF)
    • Strengths, weaknesses, opportunities and threats (SWOT)
    • Board objectives
    • Quantitative analysis
  • Step 2: Know the Capstone 1 strategic issues: In Capstone 1, JRP was facing 4 major strategic issues and several minor issues. In the Day 1 CFE exam, you’ll get 4 new strategic issues.
  • Step 3: Make note of the timeline: CFE Day 1 case is several years in the future and there are new issues to analyze. It helps to stay organized by creating a timeline of events as you are reading the case.
  • Step 4: Understand key stakeholder preferences: JRP case has several users who have opposing views. It’s important that you understand these user preferences as these will repeat in the CFE Day 1.

I strongly recommend practicing with supplemental mock exam cases. In Capstone 2, you will get 3 practice versions of the JRP case. However, most writers find that this is not enough and feel unprepared.

Where can I get extra JRP mock exam cases?

I provide one (1) original J.R. Pets (JRP) supplemental mock exam practice case to help you better prepare for the CFE Day 1. The mock exam case is a realistic simulation of what you may get on your exam and covers typical AOs that you may find in your Day 1. The casepack includes the JRP mock exam case, marking guide and the solution.

Head over to the cases section of my website for a free preview.


CPA Canada CFE Day 1 Kingsdale Tea (KTI) Mock Exam Case

The Capstone 1 Kingsdale Tea Inc (KTI) case will be tested in May 2023 and May 2024 Common Final Exams (CFEs) on Day 1. The original Capstone 1 case will be made available to candidates enrolled in Capstone 1 and released publicly later by CPA Canada.

How do I prepare for KTI case for the CFE Day 1?

On CFE Day 1, you will be presented with the same KTI case and you will be required to analyze and answer new strategic and operational issues.

Follow these strategies:

  • Step 1: Study the Capstone 1 original case well: It’s important that you know the Capstone 1 case inside-out. You will encounter the same users and similar industry challenges. I suggest making notes of the following key situational analysis factors:
    • Users
    • Mission, vision and values
    • Key success factors (KSF)
    • Strengths, weaknesses, opportunities and threats (SWOT)
    • Board objectives
    • Quantitative analysis
  • Step 2: Know the Capstone 1 strategic issues: In Capstone 1, KTI was facing 4 major strategic issues and several minor issues. In the Day 1 CFE exam, you’ll get 4 new strategic issues.
  • Step 3: Make note of the timeline: CFE Day 1 case is several years in the future and there are new issues to analyze. It helps to stay organized by creating a timeline of events as you are reading the case.
  • Step 4: Understand key stakeholder preferences: KTI case has several users who have opposing views. It’s important that you understand these user preferences as these will repeat in the CFE Day 1.

I strongly recommend practicing with supplemental mock exam cases. In Capstone 2, you will get 3 practice versions of the KTI case. However, most writers find that this is not enough and feel unprepared.

Where can I get extra KTI mock exam cases?

I have prepared one (1) original Kingsdale Tea (KTI) supplemental mock exam practice case to help you better prepare for the CFE Day 1. The mock exam case is a realistic simulation of what you may get on your exam and cover typical AOs that you may find in your Day 1. The casepack includes the KTI mock exam case, marking guide and the solution.

Head over to the cases section of my website for a free preview.


September 2022 CPA CFE Cases and Answers (Download)

Similar to prior Common Final Exams (CFEs), the September 2022 CFE had Day 1, 2 and 3 cases.

The following Day 1 cases were tested:

  • CanDo Fitness Ltd. (CFL) v1 (Download)
  • Waste Disposal Inc. (WDI) v3 (Download)

The following Day 2 and Day 3 cases were tested:

  • Day 2 (Download)
    • Tasty Meal Baskets Limited (TMB) (300 minutes)
  • Day 3 (Download)
    • STH Inc. (STH) (90 minutes)
    • TFS Ltd. (TFS) (75 minutes)
    • Brokers Inc. (Brokers) (75 minutes)

For the May 2023 CFE, the following Day 1 cases will be tested:

  • Creative Toys Inc. (CTI) v2
  • Kingsdale Tea Inc (KTI) v1

For the September 2023 CFE, the following Day 1 cases will be tested:

  • CanDo Fitness Ltd. (CFL) v2
  • J.R. Pets Inc. (JRP) v1

Where can I get the solutions?

I have written strong answers to September 2022 CFE cases. When ready, you can get them from here. 

Will I get these cases in Capstone 2?

If you are registered for the Capstone 2 module for Spring 2023, you will NOT receive these cases at the module. You should download using the links above. If you are someone challenging the exam, such as an internationally trained accountant applying under MRA/MOU, please also download using the links above.

How do I prepare for the CFE?

There are several prep methods for the CFE. You will need to focus on these three items:

  1. Technical knowledge
  2. Case writing skills
  3. Strategy

I speak a lot about these items on my YouTube channel and webinars. You can check out my latest webinar.

Technicals:

  • Know the key topics on each of the competencies
  • Distinguish depth from breadth
  • Debrief

Case writing skills:

  • It’s all about following the CPA Way
  • Know your case inside out
  • Integrate throughout the case

Strategy:

  • Prepare a study plan
  • Obtain study materials
  • Get support and resources

Pass the CPA Canada CFE Exam

I’m Gevorg. I’m an instructor and a CPA exam coach. If you want coaching with me, sign up for my CPA CFE Review Course, for a comprehensive prep package.

CFE Review by Gevorg CPA